
What to Do When No One Will Insure You
Every state has a last-resort plan that must insure you, even if every regular insurer has said no.
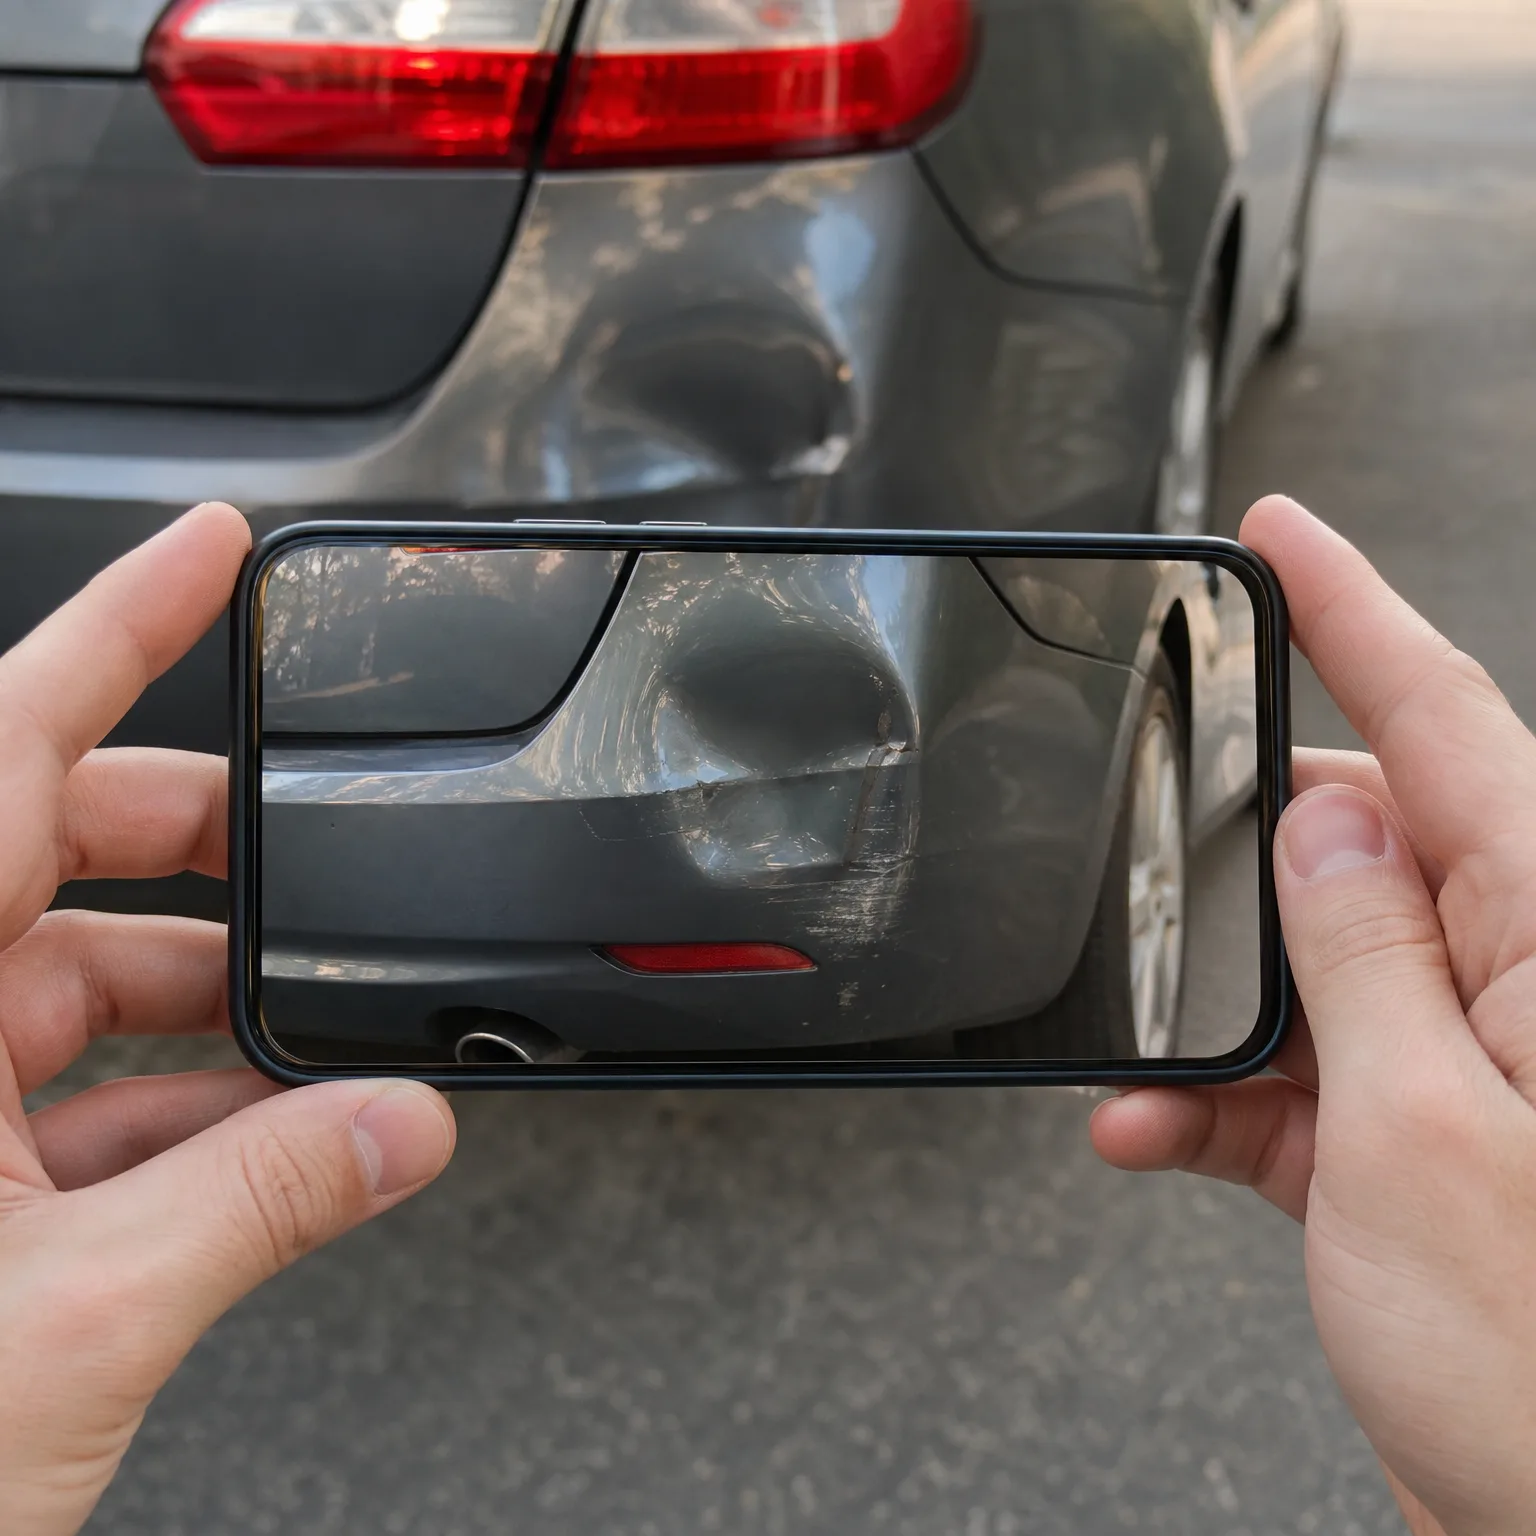
What to do when you've been turned down everywhere
- Find your state's plan Every state runs an assigned risk or shared market plan for drivers no one else will cover. Search your state name plus 'assigned risk plan' or ask any licensed agent to point you to it.
- Know why you were declined Insurers decline you for specific reasons like lapses, violations or claims history, not at random. Ask each insurer for the exact reason in writing so you know what you're working to fix.
- Use an independent agent One agent can check many insurers at once instead of you applying one by one. They also know which insurers in your state still take higher risk drivers outside the assigned plan.
- Fix the root problem A lapse, suspended license or unpaid balance is often the real block, not your driving itself. Resolve that first, since it may open doors the assigned plan alone won't.
- Plan your exit date Assigned risk coverage is meant to be temporary, not permanent. Mark the date you can requalify for regular coverage and shop again then, since the standard market is almost always cheaper.
Declined after a lapse and an accident in the same year
A driver let their policy lapse for two months while between jobs, then had an at-fault accident right after signing up with a new insurer. When that policy came up for renewal, the insurer declined to renew and the next three companies they called turned them down too. They were left without coverage and a car they still needed to drive to work.
They called an independent agent, who checked eligibility for the state's assigned risk plan and confirmed it would accept them regardless of the lapse or the accident. The agent also flagged that the lapse, not the accident alone, was what scared off the regular insurers, since it signaled risk beyond the crash itself. The driver took the assigned risk policy to stay legal and insured immediately, kept it for a year without any further incidents, and then went back to the regular market, where a standard insurer accepted them at a normal rate.
Will I be stuck with this expensive coverage forever?
No. Assigned risk and other last-resort coverage exists specifically as a bridge, not a permanent home. Insurers expect you to leave once your record improves, and most people do move back to regular coverage after a reasonable stretch of clean driving.
What keeps you there longer is leaving the underlying problem unfixed, not the coverage type itself. If the reason you were declined was a lapse, a suspension or a string of violations, insurers will reconsider you once enough time passes without repeating those problems. Set a reminder to shop again at that point, because you won't get moved automatically and the savings from switching back can be significant.
Now that you know your state guarantees you a plan, compare quotes to find the cheapest path back to regular coverage.
Applying through your state's assigned risk plan
If you do
You get a policy that meets your state's legal minimum, usually within days. You stay legal to drive and keep your car on the road while you work on the issue that got you declined elsewhere. Expect fewer coverage choices and a higher cost than you're used to.
If you don't
You risk driving uninsured, which can mean fines, license suspension or a special filing requirement stacked on top of your existing problem. Any accident while uninsured becomes entirely your financial responsibility, for as long as it takes to pay it off.
Why a guaranteed option exists and how it actually works
Insurers are businesses that choose their own risk, which means they can decline anyone they consider too costly to cover. States can't force a private company to sell a specific driver a policy, but they also can't let people be legally required to carry insurance that no one will sell them. The solution in every state is a shared plan where all insurers operating there split the cost of covering the drivers no one wants individually.
This is why the plan accepts nearly everyone regardless of history. It isn't charity or a loophole, it's a structural backstop built into how insurance is regulated. The tradeoff is that coverage costs more and choices are narrower, because the plan exists to guarantee access, not to compete on price.
What varies by state is how the plan is run, what it's called and how rates are set within it. Some states route you through regular insurers who are required to take a share of these drivers, others run a separate pooled entity. Check your state's department of insurance website for the specific name and rules, since the process for applying and renewing differs.
The cases where this doesn't apply are rare but matter. If you were declined for fraud, a canceled policy for non-payment that's still unresolved, or a suspended license tied to a legal issue, you may need to resolve that specific problem before any plan, including the assigned risk option, will issue you a policy.



