
What Can Affect Your Car Insurance Premium
Your premium is built from risk, and every factor an insurer counts is really just a way of guessing how likely you are to file a claim.
It's all a guess about risk, priced ahead of time
An insurer sets your premium before anything happens, so it has to guess how likely you are to cost them money and how much that might be. Every factor they look at is a stand-in for that guess. Your driving record predicts future claims based on past ones. Your car's price and repair cost predict how expensive a claim will be. Where you park and drive predicts the odds of theft, vandalism or an accident at all.
Some of these factors are about you directly, like tickets, accidents or how long you've been licensed. Others are about your household, since insurers often price the policy around everyone who might reasonably drive the car, not just the primary driver. That's why a spouse's record, or a teenager getting a license, can move your rate even if you never hand them the keys.
A lot of what moves the number also has nothing to do with driving. Where you live matters because local accident rates, theft rates and repair costs differ by place. How you use the car matters too, since daily highway commuting carries different odds than occasional errands. Even things like your credit history get used in many states, because insurers have found it correlates with claims, though this varies by state and some don't allow it.
This is also why the same person can get very different quotes from different companies. Each insurer weighs these factors with its own formula, built from its own claims data. One company might weigh your commute heavily and barely care about your credit, another might do the opposite. None of them are wrong, they're just different bets on the same risk.
The short version
Your premium reflects how likely an insurer thinks you are to file a claim, based on your driving record, your car, where you live and drive, and who else might drive the car. Some factors you control, like coverage choices, others you don't, like local accident rates. Since insurers weigh these differently, compare quotes from more than one before deciding.
A driver with a clean record still sees a higher quote
One driver kept a clean record for years and expected a low premium, but the quote came back higher than a friend's with a similar car. The difference wasn't the driving at all. This driver lived in an area with more frequent claims and parked on the street, while the friend had covered parking in a lower-claims area. The car itself was also more expensive to repair, which raised the cost of any future claim.
Rather than assume the quote was final, the driver asked the insurer what was driving the price and found that parking location and car model were the two biggest factors, not the record. Switching to a covered parking spot wasn't realistic, but checking quotes from a few other insurers showed one that weighed car model less heavily. The driver switched and paid less for the same coverage, without changing anything about how they drove.
Compare quotes now to find the insurer that weighs your situation in your favor.

These are the main things insurers weigh
- Driving record Tickets and accidents signal future risk to insurers. Keep your record clean going forward, since older incidents matter less over time.
- Who else drives the car Household drivers can affect your rate even if they rarely drive. List drivers accurately, since leaving someone off can cause problems at claim time.
- Where you live and park Local theft and accident rates shape your cost before you even start driving. Ask your insurer which local factors they weigh most.
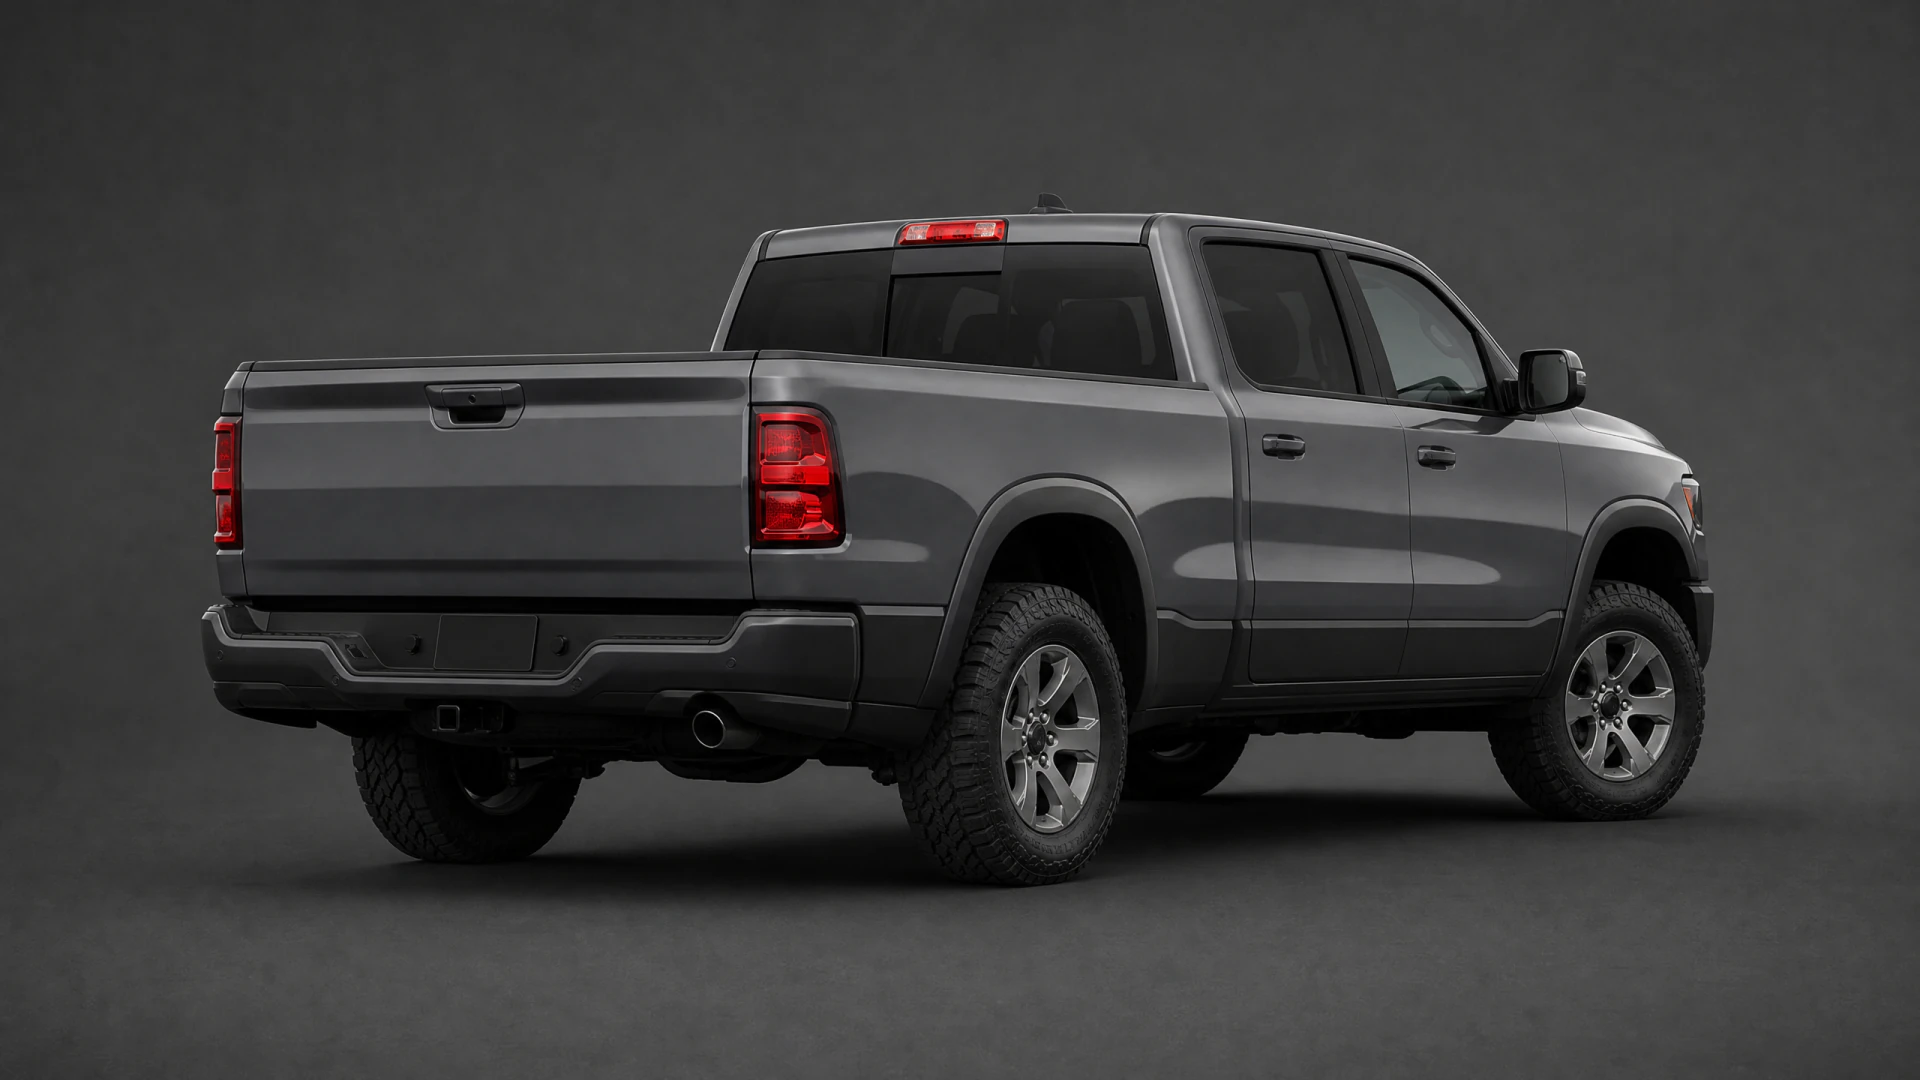
- The car you drive Repair cost, safety record and theft rates for your specific model all factor in. Check a car's insurance cost before buying, not after.
- Credit history, where allowed Many insurers use credit history as a risk signal, though this varies by state. Check your state's rules if you're unsure whether it applies to you.

Can you actually lower your premium, or is it fixed by who you are?
You can influence it, even though some factors are fixed. Your driving record, your coverage choices, your deductible, and even your car's safety features are all things you have some control over. Driving safely over time, choosing a car with lower repair costs, and adjusting your deductible to fit your budget all move the number in your favor.
What you can't change easily, like where you live or who's in your household, still matters, but it doesn't mean you're stuck with one price. Because insurers weigh these factors differently, the same set of facts about you can produce a lower quote from one company than another. That's the real lever available to you. You're not just waiting for your risk profile to improve, you're finding the insurer whose formula already treats your situation well.


